Mortgage Rates Dip to 7.24%: What This Week’s Drop Means If You’re Buying in Miami
Photo by Claudia Altamimi on Unsplash
This week’s good news: mortgage rates are down for the second consecutive week.
Freddie Mac’s average 30-year fixed mortgage rate is 7.24 percent this week. That’s the lowest it’s been since late September. (Rates are still about a point higher than they were a year ago, so I’m not popping the champagne cork just yet.)
Photo by Jason Briscoe on Unsplash.
The numbers this week
After almost two months of mortgage rates going up, mortgage rates inched down this week, marking the second straight weekly decline.
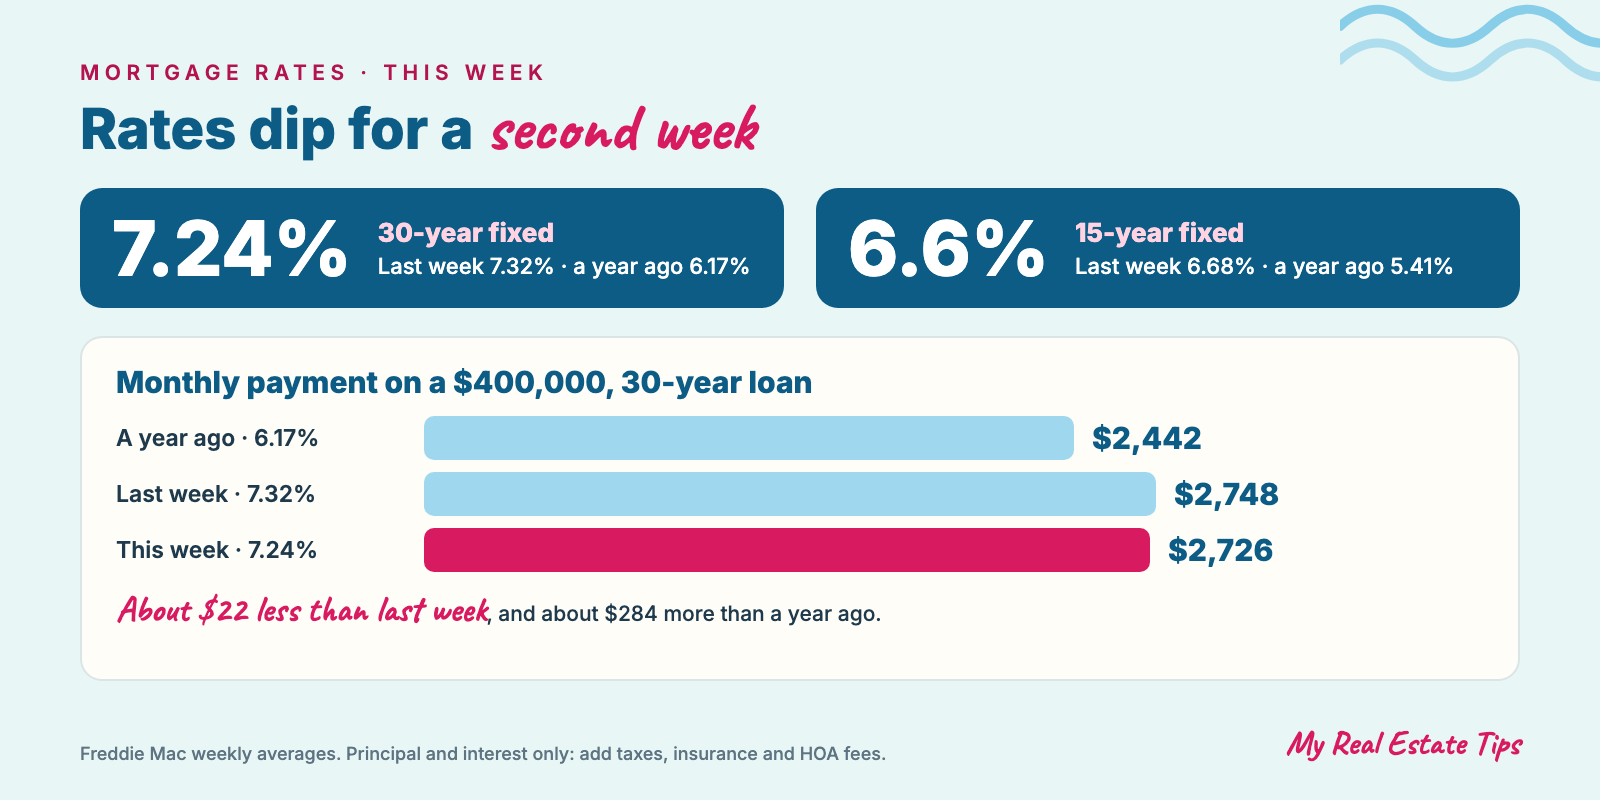
According to Freddie Mac, the 30-year fixed rate averaged 7.24 percent this week, down from 7.32 percent last week. A year ago it averaged 6.17 percent. The 15-year fixed rate averaged 6.6 percent this week, down from 6.68 percent last week. That compares to a year ago when the rate averaged 5.41 percent.
This week’s rates aren’t drastically different from last week’s, but every little bit counts, and a few extra dollars a month add up over the life of a loan. Daily rates tracked by Mortgage News Daily eased this week too.
Rates move fast, so keep an eye on them. This week’s dip in mortgage rates gives Miami home buyers slight breathing room, we’ll see if the trend continues next week. For now, we’ll take this small win.
What a few tenths of a point does to a payment
Rates fell from 7.32 percent to 7.24 percent. This may not seem like much of a difference but let’s look at some numbers.
For a $400,000 loan over the course of thirty years, the payment drops from about $2,748 to $2,726. That’s $22 less each month. Not bad, right? That’s a few extra coffees or a tank of gas each month. But, before you get too excited, let’s keep going.
Last year rates were hovering around 6.17 percent. At that rate, a $400,000 loan over thirty years would have a payment of about $2,442 a month. That means you’re paying about $284 more each month than the buyer who locked in last year. Yikes.
Now, these numbers only reflect principal and interest. If you’re buying in Florida, we also have to figure in property taxes, homeowner’s insurance and, in some cases, flood insurance. Condos will have HOA fees as well. Depending on the neighborhood, those numbers can have an even larger impact on your payment than the interest rate does.
So, while the numbers may be trending in a positive direction, it’s still important to factor in the big picture. Keep an eye on your total monthly payment.
Why the Fed meeting barely moved anything
Mortgage rates didn’t budge much after this week’s Fed decision, and the weekly average mortgage rate is likely to reflect that next week as that number is a lagging indicator.
The Federal Reserve does not set mortgage rates. While the central bank can exert some influence on long-term rates through its open-market operations and forward guidance, for the most part mortgage rates follow the bond market, and where investors think interest rates are headed.
The Fed’s decision to hold short-term interest rates steady was widely expected, and investors turned their attention to upcoming economic reports on jobs, growth and inflation. According to Jeff DerGurahian, head economist at loanDepot, markets are currently pricing in an 85 percent chance of a rate hike in December.
The forecast: higher for longer
This week’s dip is a welcome breather after all that climbing. But let’s keep things in perspective. Fannie Mae’s October forecast expects 30-year fixed rates to average 7.4 percent through the end of this year. And 7.5 percent in 2027. (In their last forecast, they expected rates to average 6.8 percent this quarter and about 6.7 percent in 2027.) So Fannie Mae isn’t predicting a return to 6 percent anytime soon. Higher for longer looks like the plan. So what should you do? Focus on the reality of the situation. Don’t count on rates coming down. It’s very possible that they won’t. Lock in what you can comfortably afford, and proceed with confidence. Hope is not a strategy. Miami isn’t going anywhere. Your life isn’t going to stand still while you wait for rates to drop. Make decisions based on reality. Not wishful thinking.
Buyers are noticing
There’s a reason so few owners are selling their homes: Most of them have a lower mortgage rate than what’s available today. And with plenty of buyers waiting too, the ones who are out there now can face less competition and have a little more room to negotiate on the right property.
Many buyers have put their plans on hold. Mortgage rates remain more than a point higher than they were a year ago, notes Joel Kan, the deputy chief economist at the Mortgage Bankers Association. But according to the MBA, applications rose for the first time in nearly two months.
Photo by Josiah Weiss on Unsplash.
What I tell buyers in Miami right now
A tenth of a point here and there is nice, but it doesn’t replace a budget.
When buyers ask me about timing, I tell them not to try to time the bottom because you will lose every single time. Instead, when the monthly number and the house work for you, that’s when you should buy. There may not be a miracle rate coming.
Also, keep in mind that your rate is different than the national average rate. Your credit, down payment and loan type all factor into your rate. Get a quote from your lender. You can also ask about a rate buydown, which is when the seller pays to lower your rate either for the first years or the life of the loan. Sellers are more open to it in a slower market, and it never hurts to ask.
Lastly, especially in Miami, don’t forget the mortgage payment is not the whole picture. Insurance, flood insurance and condo fees can all add up.
Rates could drop and you can refinance, but make sure your numbers pencil at today’s rate. Better safe than sorry.
Lock now or wait?
Let’s say you find your perfect house and the payment works with today’s interest rate. My advice? Lock and stop checking the rate every morning. Here’s why:
You can lock your rate once you’re under contract. This means, for a set number of days, your rate can’t go up before you close.
Rates could also go down. In this case, your lender may or may not allow you to get the lower rate (ask if they have a “float-down” and what it will cost).
You could also decide not to lock. If rates go down, great. You get the lower rate. If rates go up, unfortunately, so will your payment.
The bottom line is that no one knows what interest rates will do next week (yes, that includes me).
Photo by Juan Rojas on Unsplash.
If you are shopping for a condo
In Miami, a lot of buyers are shopping for condos, and the rate is only one piece of the monthly cost.
Your lender is going to look at the condition of the condo building. If there are upcoming special assessments or repairs, it may make it more difficult to get a loan.
Your condo association dues will be included in your monthly debt payments. This could affect how much your lender will allow you to borrow. This could have a similar effect as a higher interest rate and reduce your purchasing power.
In Miami-Dade, condo fees have gone up significantly since 2019. I broke down why in my piece on condo costs after Surfside. An increase in condo fees could have a bigger impact on your monthly payment than a change in interest rates this week.
Do not rush to lock in a mortgage rate for a condo. Take the time to review the condo association’s finances. Read through the budget, reserve study and any notices of special assessments. This could save you from headaches down the road.
If you’re going to make a significant purchase like a condo, do not skip steps because you’re afraid you might miss your chance. It’s better to proceed cautiously than to have buyer’s remorse later.
If you are selling
If you’re waiting for the perfect time to sell, keep reading. Even a small dip like this one brings some buyers back, and mortgage applications just rose for the first time in nearly two months. What that means for you is, your home better be looking its best. Why? Because if your home isn’t updated, or if it gives off a run-down vibe, buyers will just keep scrolling. And we don’t want that. So, keep things looking clean and presentable until your home sells. When listing a home in today’s market, it’s crucial to price it appropriately for the current buyer. With higher interest rates, this means being realistic when considering what a buyer’s monthly payment would be. Here’s a secret: Instead of offering up a price reduction, consider offering up that same amount of money as a credit to the buyer for a rate buydown. This can make your home stand out from others on the market and attract more buyers. Price it right, present it well, and be ready when those buyers come back.
This week’s rates come from Freddie Mac’s weekly Primary Mortgage Market Survey, as reported by Homes.com, along with Fannie Mae’s October forecast, the Mortgage Bankers Association and Mortgage News Daily. Payment examples are principal and interest only and are not a loan quote; your lender will give you your real numbers. For everything else that goes into the monthly cost, read the hidden costs of buying a home.
Featured photo: Claudia Altamimi / Unsplash.